All Categories
Featured
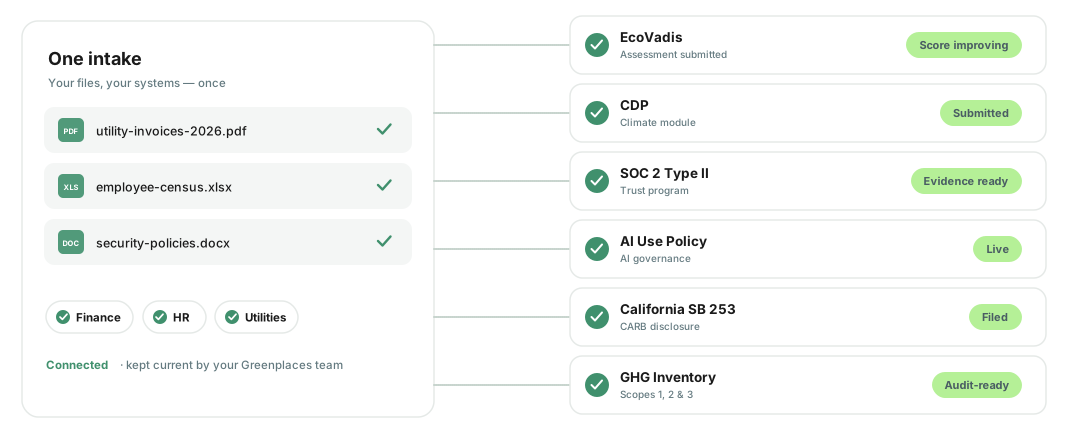
Readying Commercial Portfolios for 2026 ESG Benchmarks
Table of Contents
In 2026, the international Environmental, Social, and Governance (ESG) and sustainability landscape continues to shift and evolve. Similar to prior years, services can anticipate to navigate fragmented requirements across jurisdictions, as well as unpredictability surrounding scope and timing of regulatory commitments. The dichotomy in between deregulatory efforts in some jurisdictions and magnified regulative and enforcement efforts in others includes additional complexity to organizations' analytical techniques.
The shift from predominantly voluntary climate-related reporting to compulsory disclosures continues in numerous jurisdictions. This shift stays far from smooth cruising, nevertheless, with legal challenges and simplification procedures continuing to include plainly in the U.S. and European Union (EU). Bigger multinationals, especially, deal with a patchwork of requirements and timelines, as they must navigate converging and diverging requirements in various jurisdictions, including state-specific requirements in the U.S.
entities that "operate" in California. While a Ninth Circuit injunction has momentarily stopped briefly the enforcement of SB 261 because of its Jan. 1st statutory due date, the court did not pause enforcement of SB 253. In spite of the SB 261 injunction, CARB opened its public docket for companies wishing to voluntarily report, and a variety of voluntary SB 261 reports have actually been reviewed and released to the public, while numerous other service have picked a wait-and-see technique.
That indicates services need to assess whether any of their entities are in the scope of one or both of these bills and establish and execute a compliance strategy that is versatile as crucial details emerge or shift.: As the federal administration shifts away from climate-related threat disclosure requirements for organizations, including the Securities and Exchange Commission's (SEC) choice to end its defense the federal Environment Disclosure Guidelines, state-level legislation appears to be ramping up.
Evaluating Traditional Versus Sustainable Maintenance Standards
While a few of the proposed expenses failed to advance beyond committee stages, they may be reestablished throughout future legislative sessions. This held true with variations of New york city's Environment Corporate Data Responsibility Act, which were presented in 2022, 2024, and 2025 before SB 9072A was gone by the New York Senate on February 10, 2026.
: For the EU sustainability legal landscape, 2025 was perhaps the "Year of the Omnibus", with major legislative proposals introduced and advanced throughout the year to change the Business Sustainability Reporting Directive (CSRD), Business Sustainability Due Diligence Directive (CSDDD or CS3D) and Carbon Border Modification System (CBAM). On Feb. 24th, nearly precisely a year after first proposed, Directive (EU) 2026/470 was adopted, raising the applicability thresholds, extending timelines, and simplifying hidden requirements of CSRD and CSDDD.
: Multinationals and businesses with global supply chains must also consider their strategies within the context of the patchwork of requirements that may apply to them. Climate-related reporting is expanding well beyond the U.S. and EU, with varying requirements and timelines, including in the Middle East (e.g., Kuwait, United Arab Emirates (UAE), and Qatar) and Asia-Pacific (e.g., Australia, Japan, and Singapore).
Top Strategies for ESG Compliance in Commercial Greenspaces
As requirements and standards shift and analysis of ESG and sustainability claims increase, lots of organizations are assessing or reviewing their techniques and procedures for how and when such claims are made in order to lessen the associated reputational, political, and monetary risks. Especially, in the U.S., 2025 saw a series of examinations by unions of state attorney generals of the United States (AGs), a number of presidential executive orders (EOs), and increased investor advocacy pressing back on corporate ESG and sustainability techniques.
Private states continue to pursue legislative methods to address greenwashing threats, and in some circumstances, creating requirements that diverge from federal standards or requirements of other states, such as California's SB 343, known as the Fact in Identifying law, which has a compliance due date of October 4, 2026 but now faces legal difficulties.
Landscape MaintenanceThese dynamics equate into an expectation that green marketing and sustainability claims will remain a core concern in governance and danger management this year, challenging businesses to guarantee they preserve clear metrics, confirmed data, and transparency relating to both development and difficulties. The "social" component of ESG will likewise continue to gain scrutiny and formalization into hard law in various jurisdictions, while dealing with examinations and deregulation efforts in others, requiring international businesses (or those with international supply chains) to establish adaptable compliance and risk management methods.
This dovetails with other emerging EU requirements, such as the Required Labor Guideline, which will forbid the sale within the EU market of all items connected to required labor as of December 2027. In the U.S., enforcement under the regionally focused Uyghur Forced Labor Avoidance Act (UFLPA) began in 2022 and has actually resulted in the rejection of thousands of shipments, consisting of items presumed to be made with required labor, totaling hundreds of millions in U.S. In 2026, "circular economy" principles and associated danger will take a brand-new level of significance, driving numerous businesses to raise involved compliance and strategic structures within their business governance structures. Possibly most noteworthy in this area will be the continued increase in the number of EPR laws in a variety of jurisdictions and covering a series of products and producers.

Latest Posts
Meeting ESG Compliance in Southern California
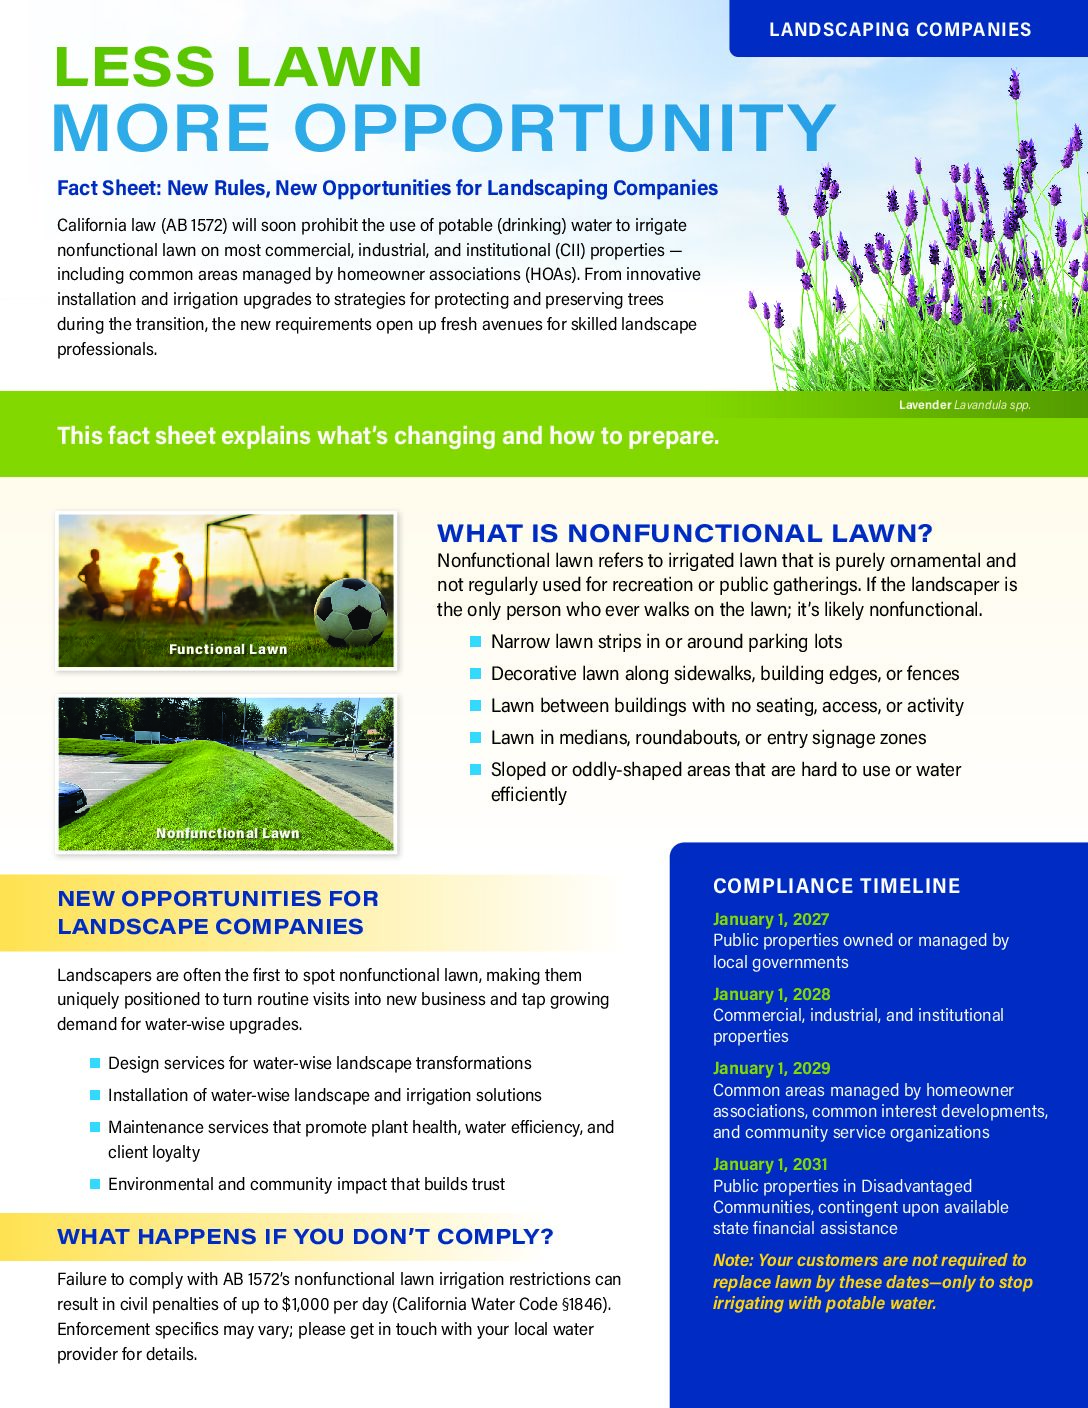
The Critical Role of Audits in 2026 Water Compliance

Scaling Sustainability Initiatives Within Los Angeles